


Close Look - What spooked the bond markets?
What has happened?
US Treasury bonds recently captured the headlines, after the yield on the 10-year bond rose above 5%1, as prices fell. Bond prices move inversely to bond yields. That compares to a yield of 4.19%2 at the start of this year. And this steep climb in yields has not been restricted to the US. Major government bond markets in Europe, as well as Japan, have seen sharp rises in yields since the beginning of the year.
- Bloomberg, BNP Paribas Asset Management, 14 September 2026
- Bloomberg, BNP Paribas Asset Management, 14 September 2026
Why now?
Let's look to the big picture first. Geopolitical tensions, such as the war in the Middle East, have brought supply chain stress to global commodity markets. As an example, the price of crude oil has jumped markedly this year, as the chart below demonstrates. This puts upward pressure on prices more generally, causing inflation expectations to rise.
Brent crude oil price, US 10Y Treasury yield and German 10Y Bund yield- 2026 YTD
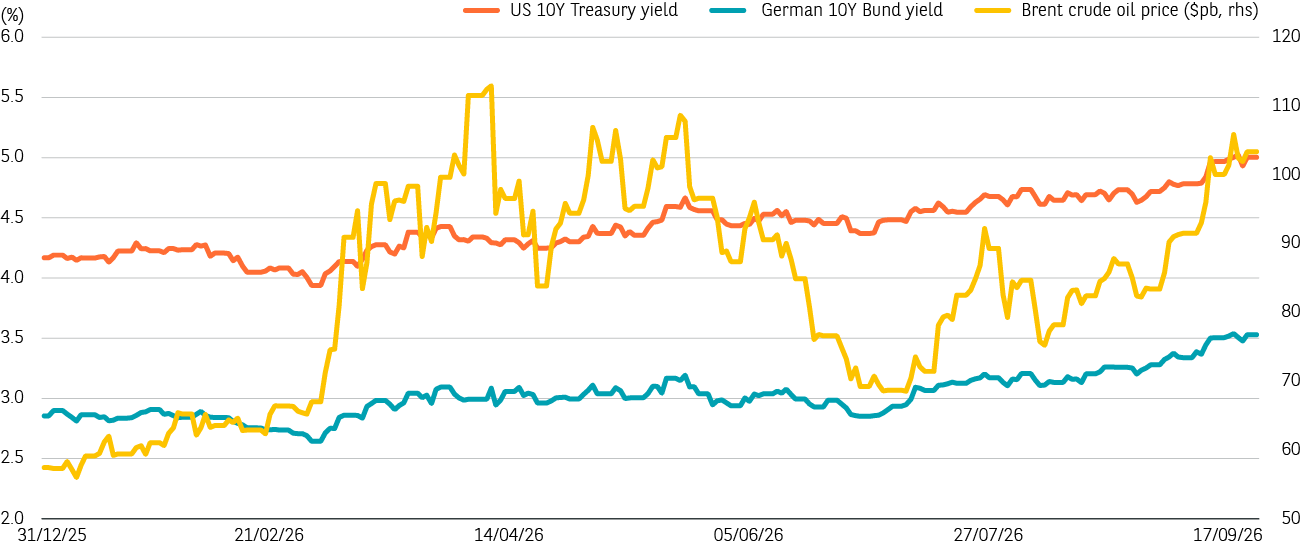
Source: Bloomberg, BNP Paribas Asset Management. Data from 1 January 2026 to 18 September 2026. Past performance does not predict future returns.
Central bank action
Rising inflation expectations generally require a response from central banks, which typically means raising interest rates. In the past month we have seen rate hikes from major central banks, including the US Federal Reserve (Fed), the European Central Bank and the Bank of Japan. What is more, the Fed adopted a distinctly ‘hawkish’ tone at its latest committee meeting, with many Fed governors showing support for further hikes in the coming months. As a result, US government bond markets have gradually changed their original expectation of no hikes this year. And bond yields have edged up in consequence.
Ballooning government debts
Government bonds, such as US Treasuries and German Bunds, are issued by governments to finance their routine fiscal spending plans. Sometimes extraordinary events, such as the Covid 19 pandemic, call for sharply higher government spending. Another example would be the initiative by Germany to boost defence spending, in response to reduced US support of NATO. The US Treasury recently announced that total debt had reached an unprecedented level of $40 trillion3. As a result, bond investors have demanded a higher level of interest on any new government debt issuance, another contributing factor to rising bond yields.
Don't forget the demands of big tech
The rollout of AI (artificial intelligence) requires massive investment on data centres and equipment such as semiconductors. Even huge companies, such as Microsoft, Amazon, Alphabet (Google) and Meta (so-called AI hyperscalers), have struggled to finance their spending from free cashflow alone, turning instead to the corporate bond markets. It is estimated that total annual AI investment could exceed $1 trillion in 20274. These demands for capital have diverted investors away from the government bond markets, which has also put upward pressure on government bond yields.
Why does this matter?
As government bond yields rise, a nation's annual interest bill also rises, diverting resources from valuable projects such as infrastructure spending. On a more technical level, the government bond yield is used as the basis for calculating the value of future earnings when determining a company’s valuation. As bond yields rise the current value of the future earnings stream falls, theoretically indicating lower equity valuations. However, current enthusiasm for the AI boom has so far allowed equity markets to look beyond these more theoretical valuation yardsticks.
Our view
As always, investors require confidence that the Fed can control inflation and that the Treasury can finance large deficits without destabilising the bond market.
Our stance on government bonds remains cautious, particularly for longer dated maturities (bonds with a longer repayment period). Inflation, geopolitical uncertainty and large fiscal deficits could keep yields under upward pressure. In this context, global high yield bonds and emerging market dollar bonds are preferred for their potential for additional yield relative to government bonds.
In the meantime, we continue to maintain a preference for equities, with broad global exposure across developed and emerging markets. This preference reflects strong profit growth, that appears to be broadening across sectors and regions.
Sources: BNP Paribas Asset Management, as at 18 September 2026
The company information mentioned (if any) is for informational purposes only and should not be construed as investment advice, a recommendation or solicitation.
All investment involves risk, including the loss of capital. The value of investments and the income from them can fluctuate and that past performance is no guarantee of future returns, investors may not get back the amount originally invested. Investors should not make any investment decision based on this material alone. Opinions included in this material constitute the judgement of the Company at the time specified and may be subject to change without notice. The Company is not obliged to update or alter the information or opinions contained within this material.
- Bloomberg, BNP Paribas Asset Management, 19 August 2026
- CNBC, 30 April 2026